 Hassan Magulumali
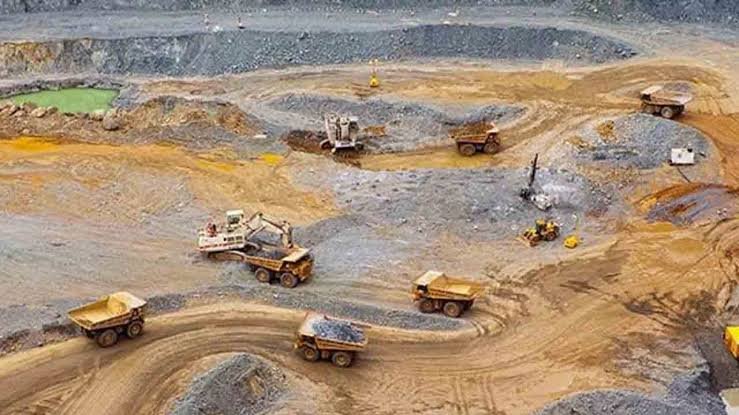
As competition for Africa’s minerals intensifies, Tanzania faces another major challenge: how to negotiate mining agreements that protect national interests over decades, rather than focusing only on immediate investment and export revenues.
The question is particularly important because mining contracts can determine who controls production, where minerals are processed, how much revenue governments receive and how much economic activity remains in local communities.
Across Africa, governments have increasingly sought to renegotiate mining arrangements and strengthen local participation.
Guinea’s Simandou iron-ore project illustrates both the scale of the opportunity and the importance of transparent agreements.
Read More: Who Will Own Tanzania’s Battery Future?
The Extractive Industries Transparency Initiative estimates that Simandou could generate between hundreds of millions and more than $1 billion annually in government revenues during its early years, potentially transforming Guinea’s public finances. However, EITI has also highlighted the importance of transparency because some key contractual information has not been publicly available.
Guinea’s experience shows why governments need to establish strong revenue-management systems before major mineral revenues begin flowing.
The country’s copper sector has experienced operational and financial difficulties, including power restrictions and major smelter disruptions at Mopani Copper Mines. Zambia’s National Assembly was told in March 2025 that operational problems had contributed to delays in payments to suppliers and contractors.
This demonstrates another risk for Tanzania: a mining project can have a large economic footprint, meaning problems at major operations can affect suppliers, workers, government revenues and surrounding businesses.
The Democratic Republic of Congo’s cobalt experience also shows the difficulty of turning resource dominance into economic leverage.
The DRC is the world’s largest cobalt producer, but its attempt to control exports and influence cobalt prices encountered difficulties because cobalt is largely produced as a by-product of copper mining. Stockpiles also accumulated when exports were restricted.
The lesson is that a government needs to understand the entire economics of a mineral supply chain before imposing or negotiating major restrictions.
Ghana is taking a different approach by requiring greater participation by locally owned mining contractors. In 2026, the country’s Minerals Commission directed several international mining companies to transition operations to local contractors, with the government saying the policy is intended to build Ghanaian capacity and retain more value domestically.
Tanzania can reduce contractual risks by ensuring that major mining agreements include:
clear and measurable local-content requirements;
transparent tax, royalty and revenue-sharing arrangements;
domestic processing commitments where commercially viable;
technology and skills-transfer requirements;
environmental rehabilitation obligations;
clear rules on changes in ownership;
protection against overly restrictive clauses;
independent legal and economic reviews before agreements are signed; and
regular public reporting on whether companies are meeting their contractual obligations.
Tanzania already has laws covering permanent sovereignty over natural resources, review of unconscionable contractual terms, local content and state participation in mining.
The challenge is ensuring that these legal protections are strongly implemented and continuously monitored.
For Tanzania, the biggest lesson from other African mining economies is that a mineral deal should be measured not only by the investment announced, but by the revenue, skills, industries, infrastructure and long-term economic capacity it leaves behind.


