 MWE Correspondent
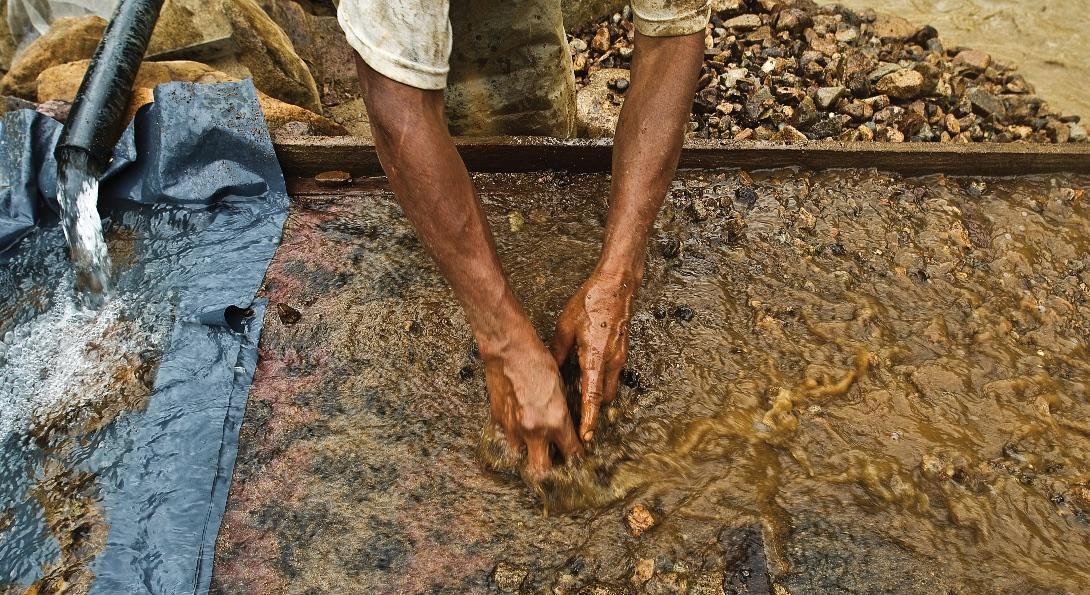
Africa’s critical-minerals project pipeline has expanded by 36% since early 2025, reflecting growing global interest in the continent’s mineral resources, but the increase in exploration and development has yet to translate into a comparable rise in actual production.
An updated database compiled by Paris-based Africa Business+ and EY shows that the number of critical-minerals projects across Africa has risen to 658, up from 483 in the first quarter of 2025.
The projects cover a range of minerals considered strategically important to the global economy, including bauxite, cobalt, copper, graphite, lithium, manganese, nickel and platinum.
However, the data points to a significant gap between the number of projects being developed and the amount of new mineral supply actually reaching the market.
Exploration projects increased by 82% to 198, while projects at the development stage rose by 70% to 129. By comparison, the number of projects already in production increased by only 11% to 288.
The figures indicate that Africa is attracting significant interest from mining companies and investors, but bringing new discoveries into commercial production remains a lengthy process.
The expansion comes as demand for critical minerals continues to grow because of their importance to electric vehicles, batteries, renewable energy, electronics, telecommunications and other advanced technologies.
Africa possesses significant deposits of many of these minerals, including cobalt and copper in the Democratic Republic of Congo and Zambia, lithium in countries such as Zimbabwe and Mali, graphite in Mozambique and Tanzania, and platinum-group metals in Southern Africa.
The increase in exploration suggests that companies are looking for new sources of minerals to meet expected future demand.
But the development process remains slow.
Read More: US Deepens Africa Minerals Push, Raising Value-Chain Concerns
According to the database, moving a mineral discovery from exploration to production in Africa can take between 15 and 17 years. This long development period means that a large increase in exploration activity today does not necessarily result in immediate increases in exports or production.
The difference between project growth and production is one of the major challenges facing Africa’s critical-minerals sector.
While hundreds of projects are being explored or developed, only a smaller proportion have reached the stage where minerals are being commercially produced.
EY senior consultant Gaël Tanguy said the figures demonstrate the tension within Africa’s mining sector, with the continent preparing future supply in response to global demand but unable to increase production at the same pace.
The situation highlights the financial and technical difficulties involved in developing new mines, particularly greenfield projects that require major investments in infrastructure, electricity, transport, water and processing facilities.
Expanding existing mines can often require less capital and carry lower development risks than building completely new operations.
Another important issue is what happens to minerals after they are extracted.
The database identifies 101 processing facilities across Africa, with significant concentrations in South Africa, the Democratic Republic of Congo and Zambia.
African governments are increasingly pushing for more mineral processing to take place within the continent rather than exporting raw ore and concentrates for processing elsewhere.
The objective is to retain a greater share of the economic value generated by Africa’s mineral resources, while creating jobs, developing technical skills and supporting local manufacturing.
This issue has become increasingly important as countries compete for investment in critical minerals.
The global transition toward electric vehicles, renewable energy and advanced technologies is expected to increase demand for minerals such as copper, cobalt, lithium, nickel and graphite.
Africa’s expanding critical-minerals pipeline is also attracting increasing attention from major economic powers seeking secure supplies.
China already has a strong presence in several African mining and processing chains, particularly in copper and cobalt. At the same time, the United States, European countries, India and other economies are seeking greater access to African mineral resources.
Recent developments involving Zambia, the Democratic Republic of Congo, Nigeria and Kenya demonstrate the growing international competition for critical-minerals projects across the continent.
For African governments, the challenge is to convert growing international demand into long-term industrial development rather than simply increasing exports of unprocessed minerals.
The 36% increase in the project pipeline therefore represents growing investor interest, but it does not by itself guarantee higher production, greater African ownership or increased local value addition.
With hundreds of projects still at exploration and development stages, Africa could become an increasingly important supplier of critical minerals in coming decades. The extent to which that mineral wealth translates into processing industries, manufacturing, jobs and broader economic development will depend on how quickly projects move into production and how much of the value chain remains within Africa.


