 Agencies
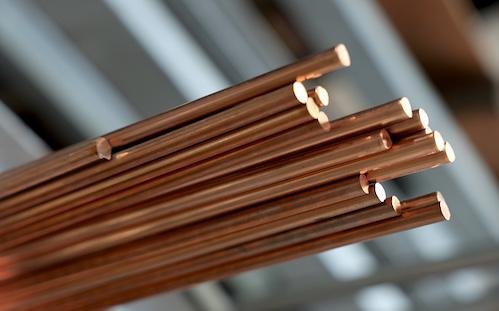
Copper is emerging as one of the most closely watched industrial commodities as prices climb to record levels, driven by rising demand from the energy transition, artificial intelligence, electric vehicles and defence industries, while concerns grow over the ability of global mining supply to keep pace.
Copper prices have surged in 2026, with the market rally also being amplified by uncertainty over possible U.S. tariffs on refined copper. Three-month copper on the London Metal Exchange reached a record $14,349.50 per metric ton on August 25, while U.S. prices have traded at even higher levels as traders move supplies into American warehouses ahead of potential tariffs.
The market’s longer-term outlook is being shaped by a fundamental question: how much copper will the world need, and how quickly can new supply be brought online?
Research by S&P Global projects global copper demand to increase by about 50 percent, from approximately 28.4 million metric tons in 2025 to 42.3 million tons by 2040.
The increase is expected to be driven largely by electrification and the energy transition, including renewable power generation, electricity transmission networks and electric vehicles, as well as growing demand from artificial intelligence and data centres.
Copper is particularly important because of its electrical conductivity and is widely used in power grids, renewable-energy infrastructure, electric vehicles, electronics, construction and industrial equipment.
S&P Global estimates that energy-transition-related copper demand alone could rise from 8.5 million tons in 2025 to 15.6 million tons by 2040. Electric vehicles also require significantly more copper than conventional internal-combustion vehicles, adding further pressure to future supplies.
At the same time, expanding mined supply is becoming increasingly difficult.
Read More: Zambia Targets 3 Million Tonnes Of Copper Production
Copper mines can require many years of exploration, permitting, construction and investment before reaching production. Existing operations are also facing declining ore grades, aging infrastructure and operational disruptions.
S&P Global projects mined copper output could peak at around 25.8 million metric tons in 2030 before declining to approximately 22 million tons by 2040. Without substantial new projects, the company estimates a potential annual supply gap of about 10 million tons by 2040.
Recent disruptions at major mines have added to concerns about supply reliability, while the continued closure of Cobre Panamá has removed a significant source of production from the global market.
However, the current price rally is not being driven by physical shortages alone.
U.S. trade policy has become a major factor in the copper market. Traders and industrial buyers have been moving large quantities of refined copper into the United States in anticipation of possible tariffs, building up inventories on the COMEX while reducing available stocks in other major markets.
S&P Global reported that COMEX inventories had reached levels equivalent to more than twice combined LME and Shanghai Futures Exchange inventories by August, illustrating how tariff expectations have redirected global copper flows.
The United States has already imposed tariffs on certain semi-finished and derivative copper products, while refined copper has remained subject to a separate review.
Under a 2025 White House proclamation, the administration was considering a 15 percent tariff on refined copper imports from January 1, 2027, potentially rising to 30 percent in 2028.
However, the White House has not made a final decision on the refined-copper tariff. Reuters reported in September that officials were weighing the potential benefits of encouraging domestic copper production against concerns that higher copper prices could increase costs for manufacturers and consumers.
The uncertainty has created an unusual market dynamic. Copper is being accumulated in the United States partly because traders want to position supplies ahead of possible duties, while inventories outside the U.S. have been reduced.
That geographical redistribution can make copper appear tighter in international markets even when total global supplies have not necessarily fallen by the same amount.
The growing importance of copper has consequently placed the metal at the centre of the global race for critical minerals. Governments are seeking greater control over mining, refining and processing as they expand electricity networks, renewable energy, electric transport, defence systems and artificial-intelligence infrastructure.
The challenge is that developing new copper mines cannot happen quickly enough to respond to sudden increases in demand. If investment in new production, recycling and processing capacity fails to keep pace, the widening gap between demand and supply could put further pressure on prices and create challenges for industries increasingly dependent on the metal.
For that reason, copper is increasingly being treated not simply as a traditional industrial commodity, but as a strategic resource underpinning the next phase of global electrification and technological development.